

1
/
16


Diagnos, Inc. (TSXV: ADK) (OTCQB: DGNOF)
Virtuix Inc. (NASDAQ: VTIX)
ATRenew Inc. (NYSE: RERE)
Vista Gold Corp. (NYSE American: VGZ) (TSX: VGZ)
Lahontan Gold Corp. (TSXV: LG) (OTCQB: LGCXF)
Forum Energy Technologies, Inc. (NYSE: FET)
Unusual Machines, Inc. (NYSE American: UMAC)
MetaVia Inc. (NASDAQ: MTVA)
Perpetuals.com Ltd (NASDAQ: PDC)
Clene Inc., (NASDAQ: CLNN)
NioCorp Developments, Ltd. (NASDAQ: NB)
First Phosphate Corp. (CSE: PHOS) (OTCQX: FRSPF) (FSE: KD0)
1
/
16
Emerging Growth Company News
Emerging Growth Research & Reports
First Phosphate Corp. (NASDAQ: FRSPF) (OTCQX: FRSPF) (CSE: PHOS) Emerging Growth...
Four Months of Exceptional Progress Materially De-Risks Bégin-Lamarche
In our view, First Phosphate has achieved a series of milestones over the past four months, advancing...

ZenaTech (NASDAQ: ZENA) Details ZenaWorx Drone-Based Construction Intelligence Platform Targeting AI...
Miami, FL--(Emerging Growth Newswire – October 20, 2026) – EmergingGrowth.com, a leading independent small cap media portal with an extensive history of providing unparalleled...

Newton Golf Company, Inc. (NASDAQ: NWTG) Emerging Growth Research Report –...
NWTG Acquires Option on Beryllium-Tungsten Property, Reiterate Buy Emerging Rating. NWTG recently announced the acquisition of an option to acquire the Pole Canyon project,...
Faraday Future Intelligent Electric Inc. (NASDAQ: FFAI) Emerging Growth Research Flash...
FFAI Announces Business Transformation; Faraday Future Intelligent Electric, Inc (FFAI) recently announced the transformation of the business to a robotaxi and EAI cabin technology...

Nevada Organic Phosphate Inc. (OTCQB: NOPFF) (CSE: NOP) Emerging...
Advancing Nevada Phosphate Exploration to Serve U.S. Agriculture
The investment case rests on Murdock Mountain’s exploration scale, a proposed physical-processing route for agricultural markets, and...

First Phosphate Corp. (OTCQX: FRSPF) (CSE: PHOS) Emerging Growth Research Report – September 23,...
SERV Letter of Intent Strengthens the Non-Dilutive Financing Stack.
First Phosphate secured support from Swiss Export Risk Insurance (SERV) for US$212.5 million toward the capital...

Newton Golf Company, Inc. (NASDAQ: NWTG) Emerging Growth Research Report – September 16, 2026
Q2 Light, But New 2.0 Shafts Drive Momentum: NWTG recently reported Q2:26 financial results that missed our expectations, as updates to manufacturing processes to...

First Phosphate Corp. (OTCQX: FRSPF) (CSE: PHOS) Emerging Growth Research Report – September 2,...
Lowering Discount Rates on Sustained De-Risking; Raising Target Price to C$5.72.
We are lowering the discount rates applied in our sum-of-the-parts (SOTP) net asset value...

Faraday Future Intelligent Electric Inc. (NASDAQ: FFAI) Emerging Growth Research Flash Report – August...
Q2 Below Expectations, but Momentum Building. Faraday Future Intelligent Electric, Inc (FFAI) recently announced Q2:26 results that fell shy of our expectations, but momentum...

Virtuix Holdings, Inc. (NASDAQ: VTIX) Emerging Growth Research Report – August 26, 2026
Forget Headlines. Revenue Growth Arrives: FY 2027 looks to beat transformational FY 2026 on new Meta partnership and defense/robotics/space/healthcare market penetration. Indeed, the Company...
Emerging Growth Research & Reports
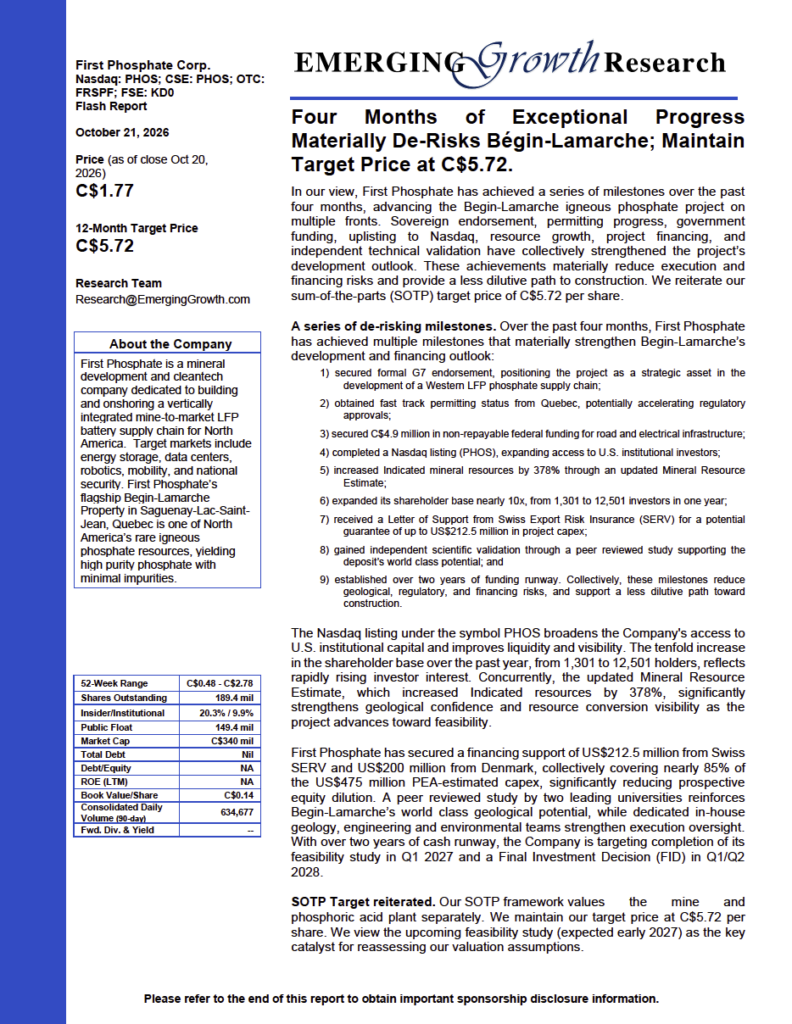
First Phosphate Corp. (NASDAQ: FRSPF) (OTCQX:...
Four Months of Exceptional Progress Materially De-Risks Bégin-Lamarche...
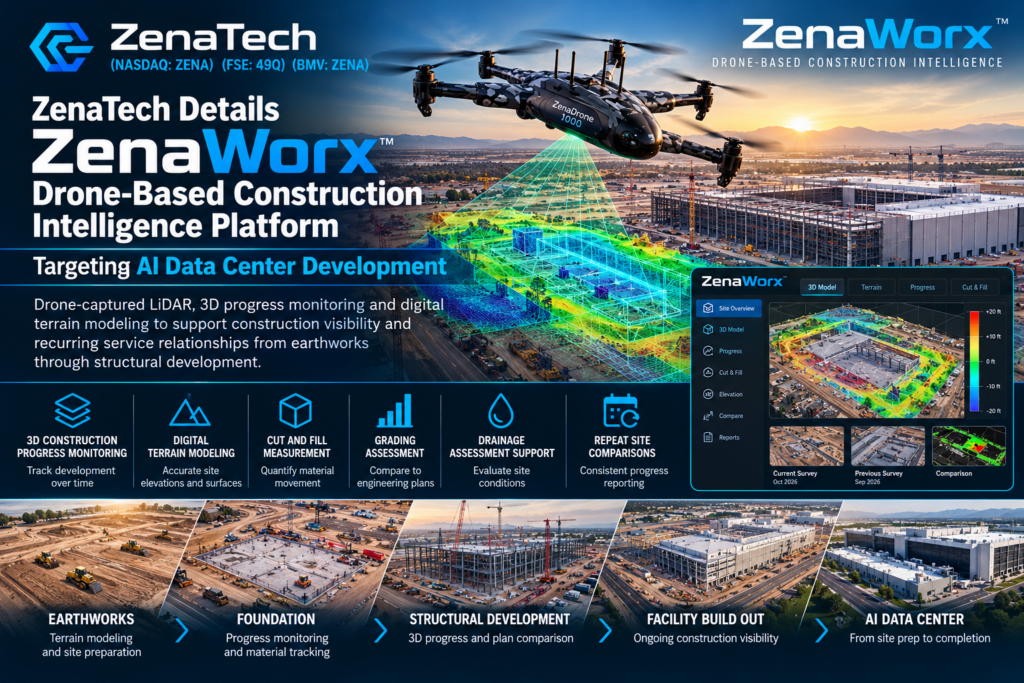
ZenaTech (NASDAQ: ZENA) Details ZenaWorx Drone-Based...
Miami, FL–(Emerging Growth Newswire – October 20, 2026) – EmergingGrowth.com, a leading independent small cap media portal with an extensive history of providing unparalleled content for the Emerging Growth markets and companies, reports on ZenaTech, Inc. (NASDAQ: ZENA). Drone-captured LiDAR, 3D progress monitoring and digital terrain...
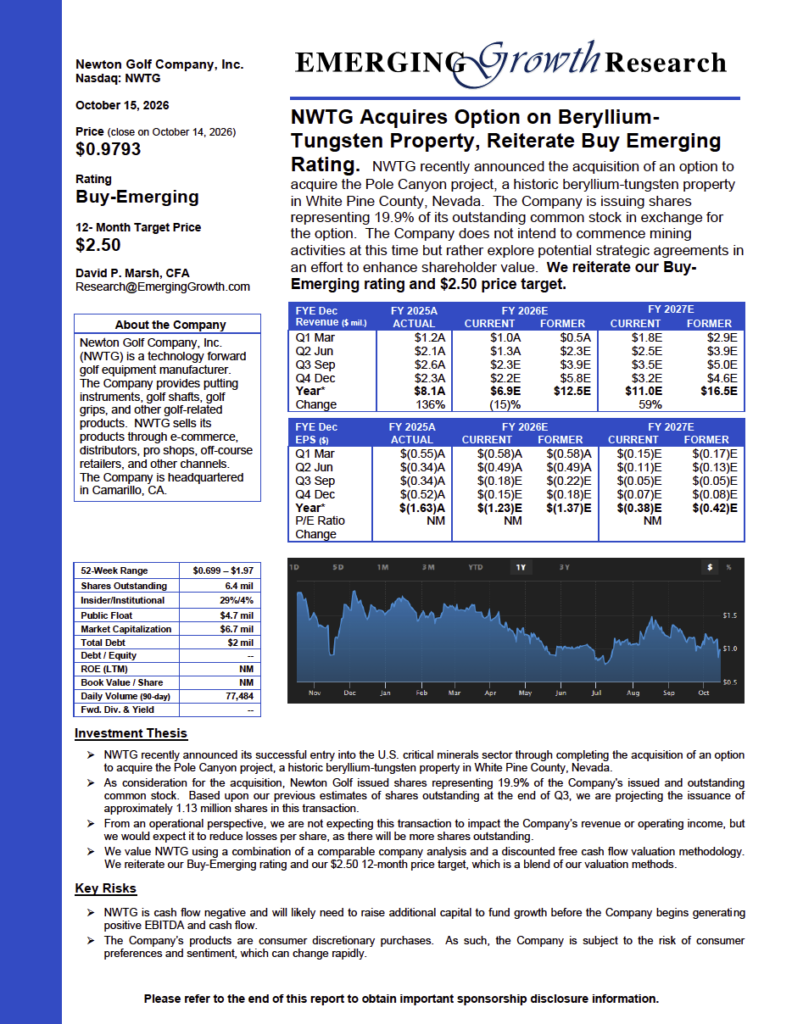
Newton Golf Company, Inc. (NASDAQ: NWTG)...
NWTG Acquires Option on Beryllium-Tungsten Property, Reiterate Buy...
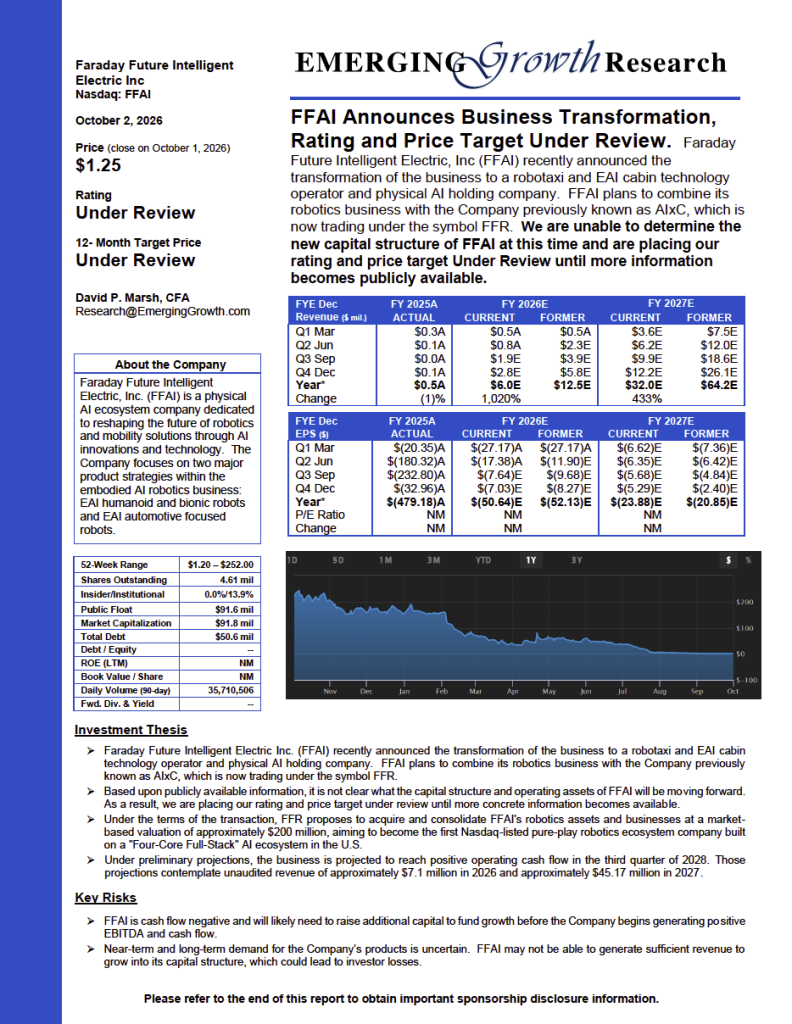
Faraday Future Intelligent Electric Inc. (NASDAQ:...
FFAI Announces Business Transformation; Faraday Future Intelligent Electric,...
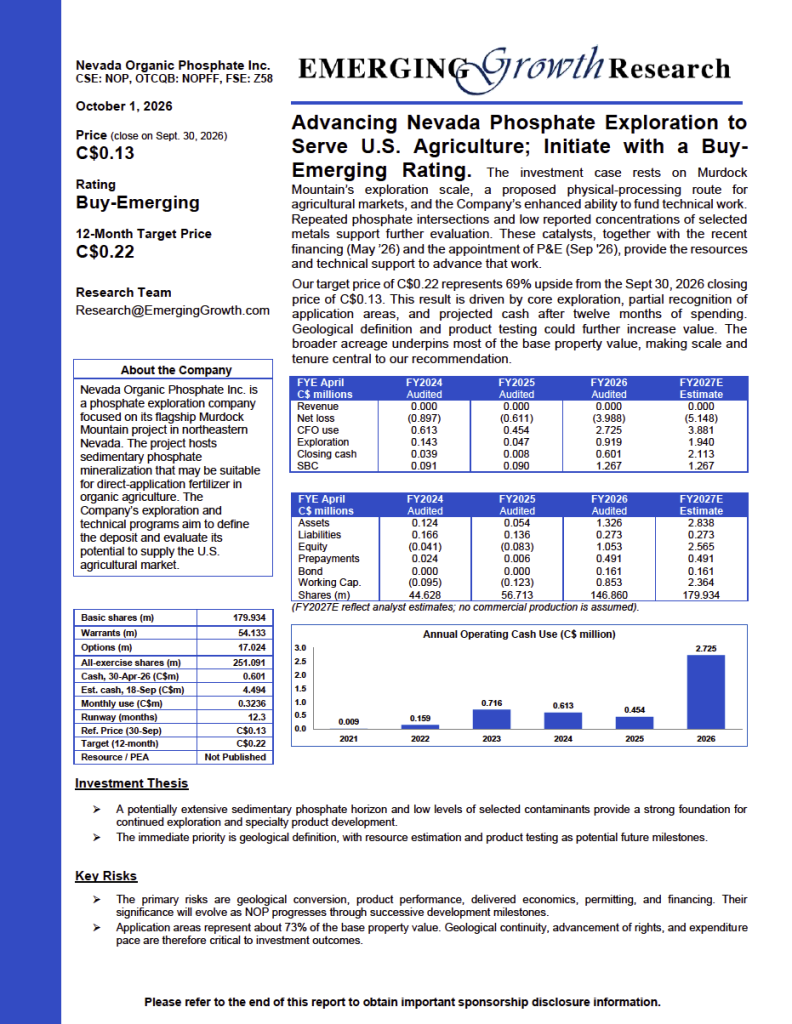
Nevada Organic Phosphate Inc. (OTCQB: NOPFF)...
Advancing Nevada Phosphate Exploration to Serve U.S. Agriculture...
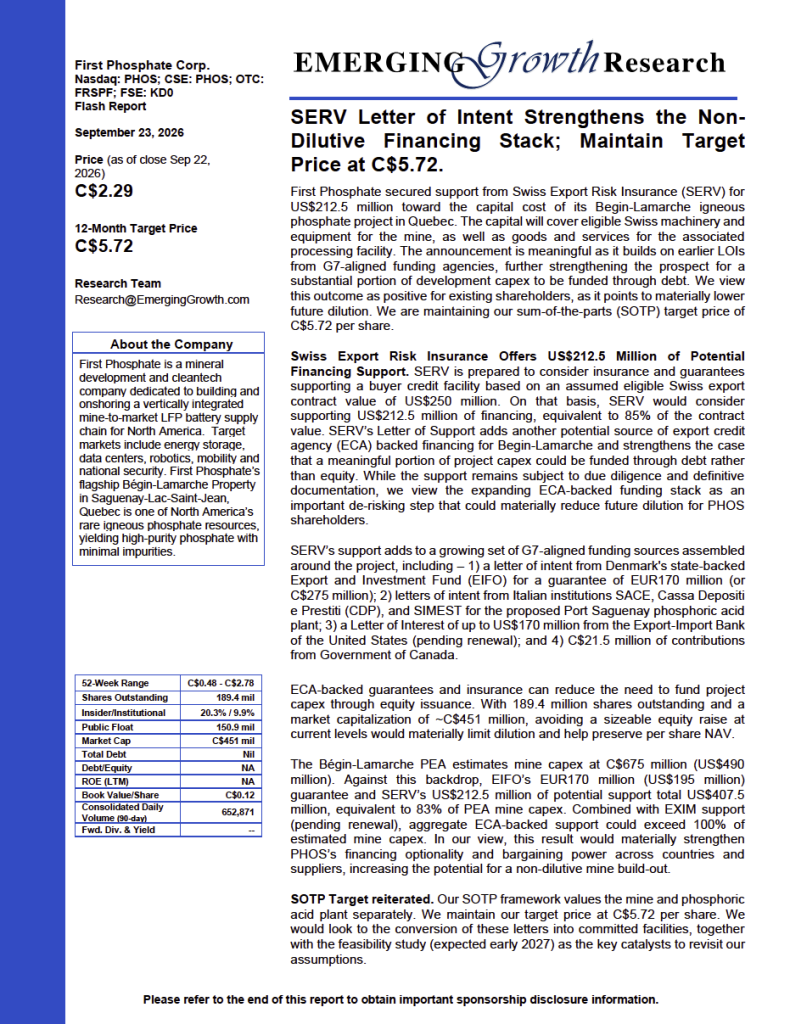
First Phosphate Corp. (OTCQX: FRSPF) (CSE: PHOS) Emerging Growth Research Report – September 23, 2026
SERV Letter of Intent Strengthens the Non-Dilutive Financing Stack. First Phosphate secured support from Swiss Export Risk Insurance (SERV) for US$212.5 million toward the capital cost of its Begin-Lamarche igneous phosphate project in Quebec. The capital will cover eligible Swiss machinery and equipment for the mine, as well as goods and services for the associated processing facility. The announcement is meaningful as it builds on earlier LOIs from G7-aligned funding agencies, further strengthening the prospect for a substantial portion of development capex to be funded through debt. We view this outcome as positive for existing shareholders, as it points to materially lower future dilution.
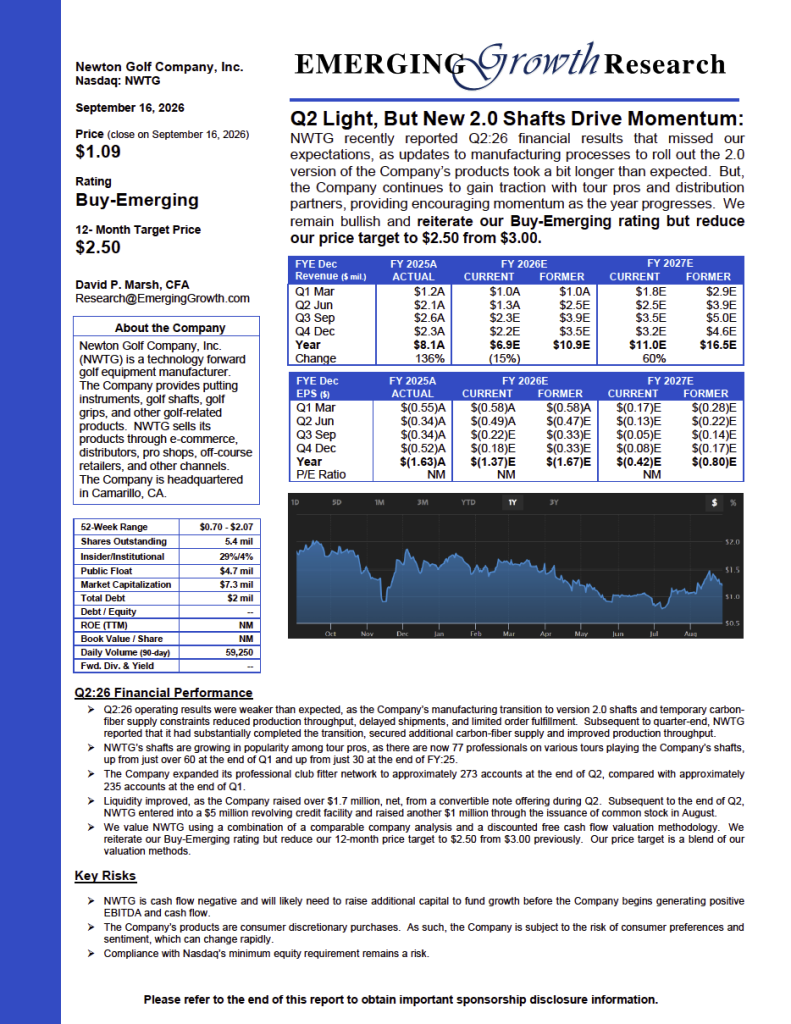
Newton Golf Company, Inc. (NASDAQ: NWTG) Emerging Growth Research Report – September 16, 2026
Q2 Light, But New 2.0 Shafts Drive Momentum: NWTG recently reported Q2:26 financial results that missed our expectations, as updates to manufacturing processes to roll out the 2.0 version of the Company’s products took a bit longer than expected. But, the Company continues to gain traction with tour pros and distribution partners, providing encouraging momentum as the year progresses.
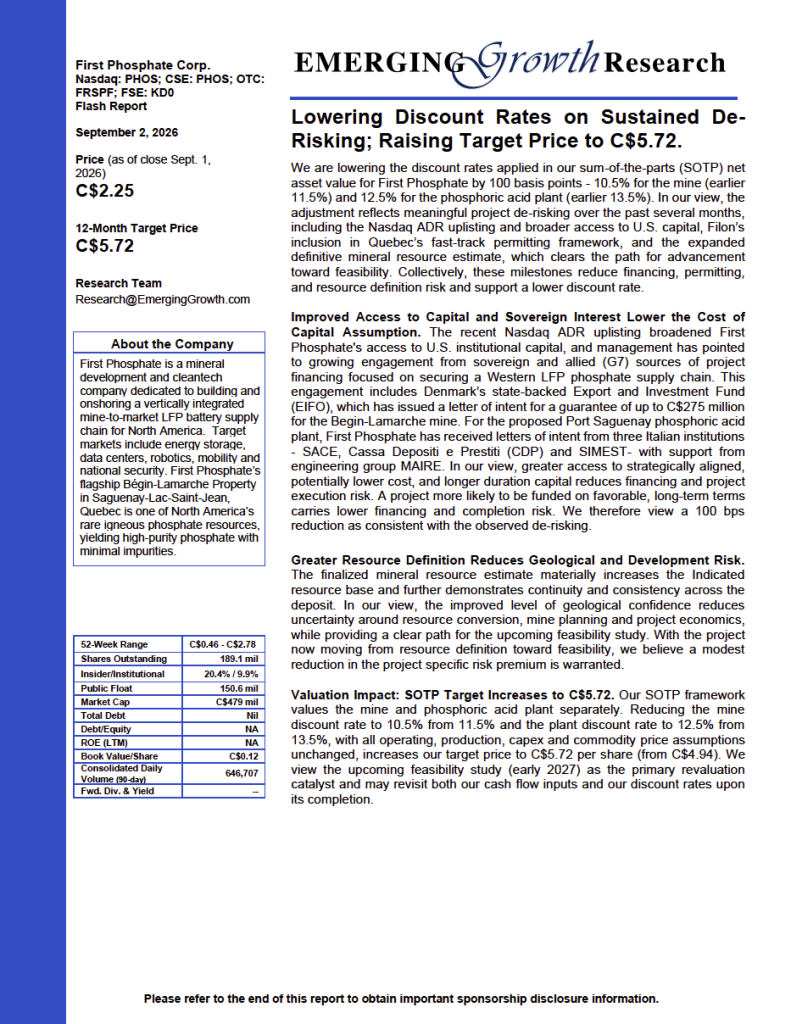
First Phosphate Corp. (OTCQX: FRSPF) (CSE: PHOS) Emerging Growth Research Report – September 2, 2026
Lowering Discount Rates on Sustained De-Risking; Raising Target Price to C$5.72. We are lowering the discount rates applied in our sum-of-the-parts (SOTP) net asset value for First Phosphate by 100 basis points - 10.5% for the mine (earlier 11.5%) and 12.5% for the phosphoric acid plant (earlier 13.5%). In our view, the adjustment reflects meaningful project de-risking over the past several months, including the Nasdaq ADR uplisting and broader access to U.S. capital, Filon’s inclusion in Quebec’s fast-track permitting framework, and the expanded definitive mineral resource estimate, which clears the path for advancement toward feasibility.
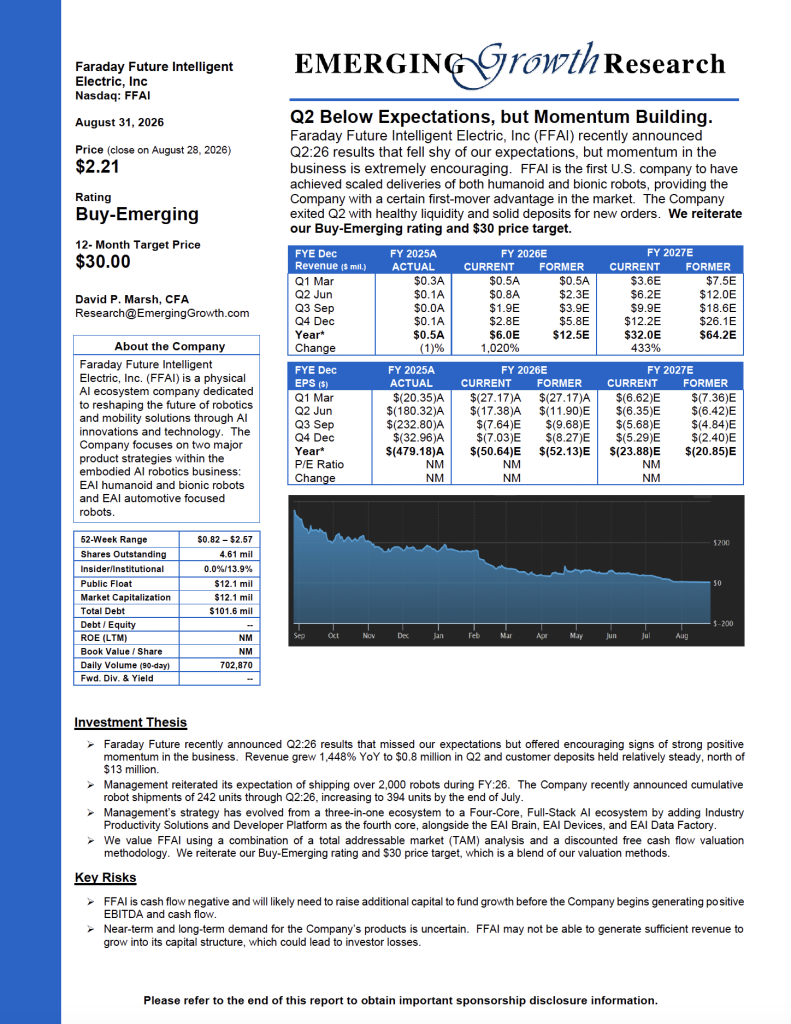
Faraday Future Intelligent Electric Inc. (NASDAQ: FFAI) Emerging Growth Research Flash Report – August 31, 2026
Q2 Below Expectations, but Momentum Building. Faraday Future Intelligent Electric, Inc (FFAI) recently announced Q2:26 results that fell shy of our expectations, but momentum in the business is extremely encouraging. FFAI is the first U.S. company to have achieved scaled deliveries of both humanoid and bionic robots, providing the Company with a certain first-mover advantage in the market. The Company exited Q2 with healthy liquidity and solid deposits for new orders.
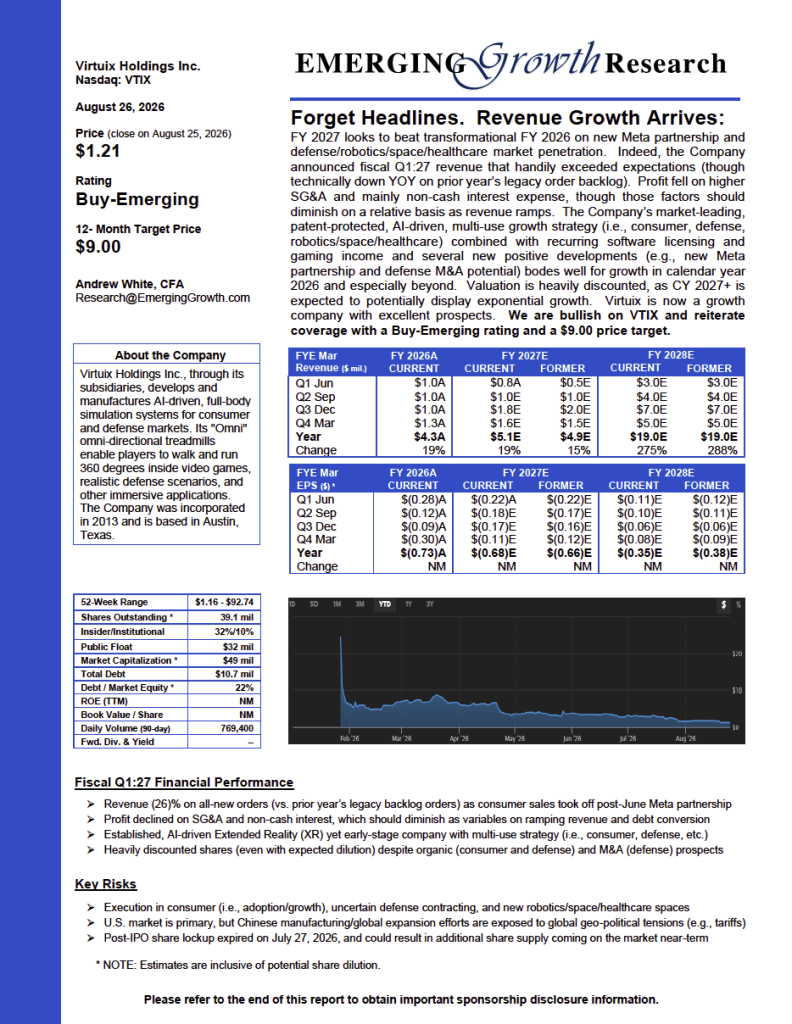
Virtuix Holdings, Inc. (NASDAQ: VTIX) Emerging Growth Research Report – August 26, 2026
Forget Headlines. Revenue Growth Arrives: FY 2027 looks to beat transformational FY 2026 on new Meta partnership and defense/robotics/space/healthcare market penetration. Indeed, the Company announced fiscal Q1:27 revenue that handily exceeded expectations (though technically down YOY on prior year’s legacy order backlog). Profit fell on higher SG&A and mainly non-cash interest expense, though those factors should diminish on a relative basis as revenue ramps. The Company’s market-leading, patent-protected, AI-driven, multi-use growth strategy (i.e., consumer, defense, robotics/space/healthcare) combined with recurring software licensing and gaming income and several new positive developments (e.g., new Meta partnership and defense M&A potential) bodes well for growth in calendar year 2026 and especially beyond.
